Comments
Comments from September 11, 2026.
The biggest story in the Southern hardwood market in 2026 has been the downturn in tie buying from railroads due to high inventories and pre-merger preparation. Given the region’s green sawmills are historically heavily dependent on selling 7×9 crossties, the situation has hit many businesses hard.
Recently, contacts have reported improving sentiments around tie purchases to HMR/Fastmarkets on both sides of the Mississippi. Their positive comments culminated in higher reported prices, with increases to the lower end of the range for Eastern ties and upper end of the range for Western ties this week.
“It’s turning,” one Arkansas-based hardwood contact said. “Quotas are loosening on my side of the river, but I think the railways have got themselves into a problem. So many mills have such low log piles now. If the treaters want ties in a hurry, they are going to have to be patient and be prepared to pay.”
Overall, supply and demand are well balanced for most Southern hardwood species. Rising interest in #1C&Btr Poplar has been noted by several sources, one of whom expressed hope that the change in season might lead to a healthier price environment.
“If you had rang me last week, I would have told you things were really slow,” one source said. “But this week has been really busy. There’s always more optimism in the South in the fall. People battle through summer and feel better in the fall.”
ASH: For both green and kiln dried Ash, the market is well balanced. Lowland timber tracts—where Ash usually grows in the South—have been accessible most of the summer, allowing consistent production in areas not decimated by Emerald Ash Borer. The only price changes this week are increases for green 6/4 and 8/4 Fas&1f, showing there is good interest in thick Ash.
#2A&3A OAK: After recent increases, prices for #2A&3A Oak have generally leveled off over the last two weeks. Increased purchasing by residential and truck trailer flooring plants, both within and outside the region, drove the upward movement. This was welcomed by Southern sawmill operators, who have endured a challenging 2026. Truck trailer flooring plants, in particular, are known to be reaching out to mills for larger quantities of 5/4 #2A&3A Oak.
RED OAK: Production and consumption of kiln dried #1C&Btr Red Oak are well matched, both at relatively low levels. Chinese interest has slowed since mid-summer, whereas domestic demand is steady. Previous adjustments have all dry-stock prices in order. While sawmill contacts say green Red Oak is still moving, few describe it as one of their best-sellers. The only changes to published green prices are slight bumps to 5/4 Fas&1f.
WHITE OAK: White Oak remains in a similar place as Red Oak in terms of overall market conditions. While showing signs of firming at times, demand for green White Oak remains merely steady and is easily met by available supplies from sawmills. One Arkansas contact talked up decent price bounces for uppers, though reported prices only increase the green 5/4 Fas&1f and 6/4 #1C listings this week. On the kiln dried side, the listings for 5/4 #1C and 4/4 #2A move up. Interest in White Oak is down from China but up from Vietnamese and European buyers.
POPLAR: Despite the relative lack of price movement for Poplar, contacts report the species is selling better. “The Poplar market is good for me, especially #1C&Btr,” a Georgia-based hardwood seller said. “Anytime we have an inventory of #1C, it seems like an order comes in straight away.” A Mississippi source backed these comments up, adding, “It feels like uppers are moving but [lower grades] have slowed down.” Amid solid domestic activity, the listings and ranges for kiln dried 4/4 Fas advance in this issue. Conversely, the 6/4 #1C&Btr and 5/4 #2A listings fall back.
BOARD ROAD, FRAMESTOCK, CANTS & TIES: Loosening crosstie quotas by treaters and higher prices in selected transactions drive increases to the upper end of the range for ties west of the Mississippi River and lower end of the range east of it. Markets for mat timbers, crane mats, and board road remain buoyant. Reported prices increase the listing and range for board road.
Demand for Oak and Mixed Species framestock is sluggish, and the respective ranges hold at previous levels. The pallet cant market stayed cold, with all reported prices comfortably covered by the HMR range.
Comments from September 11, 2026
Surveys of Appalachian region sawmills indicate log supplies are level to slightly lower now than in August, while green and kiln dried lumber sales are mostly fair. However, there is a disconnect between the “slow,” “fair,” and “good” survey ratings compared with the lengthier written market descriptions and from notes taken during phone calls with industry contacts. Slow, low, and quiet are commonly used adjectives describing demand for grade lumber items, mainly from Asia. Exporting mills and yards have reported steady-to-slower shipments to Europe in recent weeks, but contacts expect some post-vacation season replenishing. “We are looking forward to foreign markets getting back from their vacation holidays,” a yard contact said. Domestic interest has “woken up” in early September, according to another contact. That sentiment isn’t region-wide, however, as transactions between many sellers and buyers are for short-term, immediate needs at flat-to-lower prices for several items.
ASH: The marketplace is readily absorbing green 4/4 and 6/4 Ash at prices centered on the #2A&Btr listings. Demand for 5/4 exceeds supply, however, prompting gains to all 5/4 stock. Conversely, transactions for 8/4 #1C&Btr reveal downward bias that lowers the listings. Weakness is evident in reported kiln dried 6/4 Ash prices. The listings for #1C and #2A are lowered by $20 per thousand board feet ($20/MBF).
BASSWOOD: Supply-driven price pressures have lowered the listings for certain green items in recent weeks. Supply and demand are now more closely aligned, however, keeping all green figures intact in this edition. Likewise, no changes are required to any kiln dried figures.
CHERRY: With red appearances out of favor in North America, domestic sales of Cherry remain anemic. Solid consumer demand for this species drove increased purchasing by secondary wood products manufacturers in China earlier this summer, but interest has slowed over the last couple of months. Reductions in prior weeks across each producing region have all published green and kiln dried prices in order.
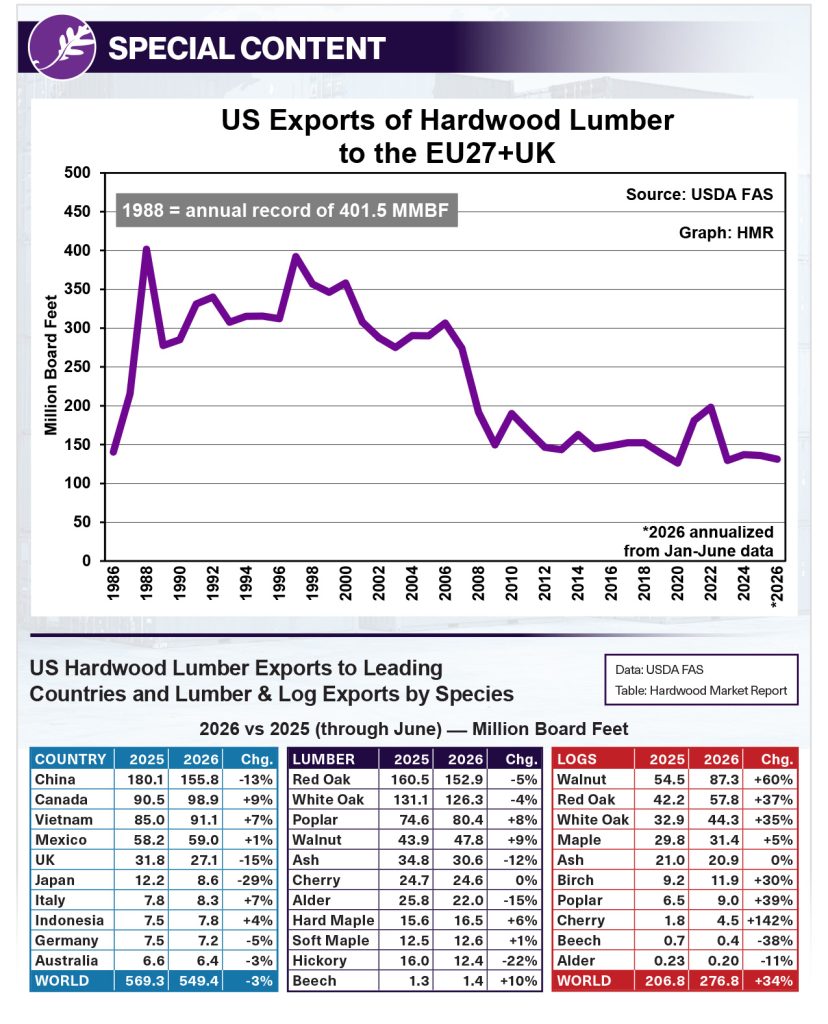
HICKORY: Residential flooring plants are sourcing sizeable volumes of #3A&Btr Hickory, responding to an uptick in finished goods sales amid an overall market environment that has been busier in the second half of the year thus far. The listings for #2B are raised across all thicknesses. US exports of Hickory lumber were down 22% year over year through July, with shipments lower each month thus far in 2026 than in the corresponding months in 2025.
HARD MAPLE: Hard Maple sales are slow across most grades in both green and kiln dried markets. Sales to cabinet manufacturers have been flat-to-lower over the last few weeks, while cabinet manufacturing operations report adequate lumber inventories for their current production levels. Amid tepid market conditions, reported prices continue to decline. The green 4/4 through 8/4 Fas&1f listings are reduced in both color designations, as are the listings for 5/4 through 8/4 #1C. Reported kiln dried prices are also retreating. Information is sufficient to lower the listings and noted ranges for 5/4 through 8/4 Fas and 4/4 #2A in each color classification. The high-end ranges for #1&2 White 4/4 #1C also lose ground.
SOFT MAPLE: This species appears frequently on sellers’ lists of slowest-moving items. According to one yard contact, “Soft Maple is a big concern for us and others in our area because it has been such a stalwart in the market, the best domestic item with the best margin for several years.” However, a sawmiller reports steady sales of #1C and #2A at stable prices, and that his previous concerns about rising inventories have waned with a regular customer wanting larger monthly volumes. Reported kiln dried prices support most existing listings and ranges. However, 5/4 Fas is the exception, with lower observed prices prompting decreases to the listings in each color sort. Meanwhile, the green 5/4 Fas&1f and 4/4 #1C listings are reduced in both color selections, as are the Unselected 4/4 Fas&1f figures.
#2A&3A OAK: Oak strip flooring sales have gained more momentum, but more so for Red Oak than White Oak. Raw materials are available at stable prices. Truck trailer flooring producers are relatively less busy, with lumber inventories sufficient for current production rates. Concentration yards with export programs are being cautious with lumber purchase volumes and prices for Red Oak and White Oak. Healthy demand for pallet cants is helping to keep #2A&3A production controlled. No sector is having an outsized impact on demand or prices. Collectively, however, the sectors are absorbing total #2A&3A output at prices grouped around the listings. Similarly, no change is required to the listing for #2A Alone Red Oak.
RED OAK: Domestic Red Oak sales prices are holding up fairly well, whereas softening Chinese demand has pressured export prices lower in recent weeks. Some contacts say they are hearing price offers for kiln dried #1C&Btr well below the published figures. However, reductions in recent issues have all the listings and ranges in order. In green, the $20/MBF declines to the listings for 5/4 through 8/4 Fas&1f are reflective of transactional data.
WHITE OAK: Demand is better for White Oak than for several other species, based on how frequently it makes contacts’ best-seller lists. Mills are shipping total green production at prices consistent with the #3A&Btr listings. On the dry side, sales are stronger for Fas than for #1C and #2A. However, 4/4 Fas supplies are again outpacing decent demand, continuing the recent downward price trend that appeared to be over after the listings didn’t budge for nearly three months. Reported prices warrant reductions to the 4/4 Fas listings. Incoming reports also lower the listings and ranges for 4/4 #2A but hold all other kiln dried thickness and grade combinations steady.
POPLAR: Some concentration yards are finding it harder to procure Fas&1f Poplar. Meanwhile, #1C and #2A Poplar supplies are adequate to oversupplied, according to a large wood products manufacturer that also reports brisk finished goods sales, low finished goods inventories, and healthy monthly Poplar purchases. No changes are necessary for any green listings this week. At the same time, reported kiln dried prices are retreating for several items, requiring decreases to the listings and noted ranges for 4/4 #1C&Btr, 5/4 #1C&Btr, and 8/4 #1C.
WALNUT: Concentration yards have become somewhat more active with purchases of this species, coming off a slow period in mid-summer. Observed prices for green 4/4 and 5/4 Walnut items are mostly grouped around the published figures, as is also the case for 6/4 and 8/4 #1C and #2A. However, information reveals downward trending prices for thicker-stock items that lower the listings for 6/4 and 8/4 Fas&1f by $30/MBF and $50/MBF, respectively. Kiln dried 4/4 activity remains stronger for #2A than for #1C and Fas. Survey results lower the listings and ranges for 4/4 Fas, and the listings for 6/4 Fas also decline. Despite reported strength in #2A relative to the other grades, the 5/4 #2A listings and low-end ranges retreat amid lower reported prices.
FRAMESTOCK, CANTS, TIES, & BOARD ROAD: Well air-dried framestock inventories are adequate to supply limited demand. Reported prices are mostly unchanged and keep the Oak and Mixed Species ranges in check.
Mills are readily shipping their full cant production. Many describe business as quite good. Gains in prior weeks are sufficient to hold the listing and range steady in this edition.
Demand for railroad ties lags in comparison with cants yet is stronger than for other low-grade items listed in weekly surveys. Markets are absorbing supplies that are still limited by quotas in many areas at prices within the 7×9 crosstie ranges.
Data centers drove all nonresidential construction spending growth in July, according to analysis by Associated Builders and Contractors. This lends support to anecdotal reports from industry contacts about the influence data center construction is having on demand for board road and crane mats. Current board road production levels are satisfying the market’s needs, however. Reported prices are well represented by the listing and range.
Comments from September 11, 2026.
Elevated freight costs have been one of the biggest factors eroding Northern hardwood producers’ margins this summer. Recent comments about this matter are still extremely negative, with some contacts describing freight as their biggest problem. The US on-highway diesel price averaged $5.60/gal on August 31, up from $3.48/gal at the start of 2026. Market participants have been forced to share higher costs with truckers or attempt to pass them on through increased lumber prices. However, this is difficult in the current times of weak demand for grade lumber, so many producers are “eating” the higher fuel costs.
ASH: The green Ash listings rise across all grades and thicknesses this week. Numerous higher sales prices reported by buyers and producers prompted the widespread gains. As we’ve reiterated many times, the Emerald Ash Borer is severely constricting supplies of Ash in the North. This limited production is being outstripped by firm domestic demand, leading to consistent price gains for both green and kiln dried Ash throughout this year. Additionally, kiln dried Ash is drawing plenty of interest from Chinese customers, according to contacts, despite the broader slowdown in shipments to the Far East nation. Prior adjustments have all kiln dried listings and ranges in order.
ASPEN: Though Northern producers still report steady inquiries for kiln dried Aspen, some have had to lower offer prices recently in order to move their existing inventories. Consequently, several dry-side decreases are required to published prices this week. The Fas listings and range numbers all fall, along with the #1C listings and both ends of the #2A ranges. All green listings are steady. Also of note, in a somewhat unusual occurrence, an Aspen producer in the Upper Midwest told HMR/Fastmarkets that he received inquiries from Chinese buyers for Fas Aspen.
BASSWOOD: There’s not much new to say about the Basswood market that hasn’t been stated in recent commentaries. Most producers are struggling to move the species, outside of those with established customer bases. Domestic window blind and shutter manufacturers have ample inventories and are, therefore, controlling purchases. Green and kiln dried prices are maintaining a steady-to-firmer posture, largely driven by limited production. No changes are necessary this week to any listings or range numbers.
BIRCH: Northern producers have been struggling to move Unselected Birch all summer. Buyers are primarily interested in Sap&Btr, which is selling for substantial premiums. Recently, sharply lower prices have been reported for kiln dried Unselected Fas Birch. This week, those listings and ranges fall again, extending last week’s steep declines. The net 4/4 Fas listing is down $160 per thousand board feet ($/MBF) in the past two weeks, sliding to the lowest level since November 2020. Green 4/4 through 8/4 Fas&Sel prices are similarly pressured, and those listings fall again this week, by $50/MBF. Low-grade Birch is less readily available than #1C&Btr, as strong industrial markets are eating into supplies. The kiln dried 4/4 #2A listings and high-end range numbers are raised this week in accordance with firmer reported prices.
HARD MAPLE: Green Hard Maple prices have been under downward pressure for roughly the past two months, as July highs are now clearly in the rearview mirror. Demand for the species is ongoing, according to sales contacts, some of whom still list it as a best-seller. However, market conditions are less favorable, and high temperatures have forced green producers to regularly lower sales prices to move lumber prior to staining. The green 4/4 and 5/4 Fas&Sel listings fall further this week in both color sorts, sinking to the lowest levels since the spring of 2024. Green prices have been more stable for the common grades than for Fas&Sel during the last few weeks. Kiln dried Hard Maple prices were steady well into the summer, but prices came under pressure in the second half of August due to the green slide and comments about demand shifting from almost universally positive to more mixed. This week, consistent reported prices hold all kiln dried listings and ranges steady.
SOFT MAPLE: Most producers are having trouble moving kiln dried Sap&Btr Soft Maple, as all grades have been among contacts’ worst-sellers in recent weeks. Many have recently noted excess supplies of kiln dried #2A in Northern markets. This is evident in reported prices this week, necessitating decreases to the 4/4 #2A listings in both color classifications. All other kiln dried listings and ranges are unchanged. On the green side, the 4/4 through 8/4 #2A listings are raised in both color sorts, along with all the Unselected #2B listings. As is the case with other species, red-hot industrial markets are constricting low-grade supplies. Conversely, the Unselected #1C listings fall across thicknesses because of lower prices in observed business.
RED OAK: The kiln dried 4/4 Fas Red Oak listings are lowered this week, the only adjustments in an otherwise steady week for the species pricewise. The summertime slowdown in Chinese purchasing is putting consistent downward pressure on #1C&Btr Red Oak prices, though domestic demand has been steady enough to keep prices from falling sharply. Green and kiln dried prices are still well above start-of-year levels, despite decreases over the course of the summer. Green #1C&Btr markets are adequately supplied amid seasonally higher production, though not all flooring manufacturers are satisfied with #2A&3A availability. Overall, the Red Oak market is in a steady-to-softer posture. A rebound in Chinese demand will likely be needed for prices to stabilize.
WHITE OAK: Kiln dried Fas White Oak is moving well for producers in the Northern region, and higher reported prices prompt $50/MBF increases to the listings this week. One producer in the Upper Midwest told HMR/Fastmarkets that they “wish they had more Fas to sell.” The price spreads on Fas items are extremely wide, especially when considering premiums garnered for loads with high percentages of 9-foot and longer stock. Comments about kiln dried #1C and #2A are muted, as Fas is the best-moving grade. In green markets, #1C&Btr prices are facing downward pressure from excess supply, while #2A&3A prices have firmed recently on the back tight supply. No adjustments are necessary for any green listings.
PALLET LUMBER, CANTS, TIES, & BOARD ROAD: Prices for pallet cants and lumber are consistent with prior weeks, holding all listings and ranges for those items steady. Comments about demand from the pallet industry are almost entirely positive for producers in the Upper Midwest and Northeast Canada, and prices are maintaining a steady-to-firmer posture.
In the crosstie market, many producers in the Upper Midwest are operating without quotas due to increased purchasing by area treatment plants. The big question is how long that uptick in demand will last, and contacts themselves are wondering the same thing. For now, though, the 7×9 crosstie price range is unchanged amid consistent reported prices.
Similarly, the Northern board road listing and range are steady this week, as no substantial changes have occurred in the market. More mills are cutting board road than in the past, and demand has been high enough to absorb the additional output.
Comments from September 11, 2026.
Spending patterns by US consumers are seasonal. Discretionary expenditures during the summer are typically focused on vacations and outdoor activities instead of the interior of the home. Spending priorities shift back to the interior in the fall, after Labor Day, once households have wrapped up vacations and buckle down for another school year, cooler weather, and fewer daylight hours.
As of this publication date, there are 11 weeks before the US Thanksgiving holiday. That tends to be an important date for homeowners tackling renovation projects because the goal is to have work wrapped up in time for Thanksgiving. This leaves adequate time for installing new unfinished Oak flooring, allowing coatings time to dry, finishing trim work, and reconfiguring furniture and accessories. Accordingly, it is not unusual for activity in the Oak strip flooring market to pick up ahead of the holiday season.
Collectively, the data variables that drive Fastmarkets’ Repair & Remodeling Index (RRI)—inflation-adjusted retail sales at building materials dealers; aggregate hours worked by residential remodelers; and the volume of Google searches involving do-it-yourself home improvement and replacement projects—have collectively pushed the Index higher since early 2024. Year-over-year through July 2026, the RRI was up 7.1% on a seasonally adjusted basis.
However, one of the aforementioned Index drivers is having an outsized impact on the RRI. The Google search trend component has risen strongly alongside widespread adoption of Google’s AI chatbot, Gemini, which appears to be changing the relationship between search volume and actual activity, according to Fastmarkets economists. In other words, that component could be skewing the Repair & Remodeling Index higher despite tepid performances by other components. When accounting for that, research shows the RRI reading is virtually unchanged on the year through July, albeit from strong levels in 2025.
Most flooring items are moving at a healthy pace and have been since mid-July, shifting producer comments to a decidedly more positive tone and portending a stronger seasonal finish than start of the year. Changes in this week’s pricing matrices reveal continued downward pressure on Sel&Btr White Oak flooring but continued upward momentum for Sel&Btr Red Oak.
August 28, 2026